The most useful fintech number is not a market size, it is a proportion. Fintech companies captured roughly 5% of global banking revenue in 2024, which places every disruption claim in context. This page leads with that proportion, covers the lending and payments data that is genuinely well sourced, and explains why published fintech market sizes disagree by nearly tenfold. Analysis of what the numbers mean is covered separately.
Fintech’s Actual Share of Banking
This is the single most clarifying statistic in the category, and it appears far less often than market size projections do.
The Revenue Share
(cite index=”45-1″>Fintech companies captured approximately $150 billion in banking revenue globally in 2024, about 5% of the roughly $3 trillion total banking revenue pool, per McKinsey’s Global Banking Annual Review 2024.</cite>
The Projection
(cite index=”45-1″>That share is projected to reach 8 to 10% by 2030 as embedded finance scales and AI-driven cost reduction expands fintech’s addressable market.</cite>
What 5% Means in Practice
Fintech has taken a meaningful slice of a very large pool rather than displacing incumbents. Both the disruption narrative and the dismissal are wrong.
Why This Frames Everything Else
A category at 5% share with a path to 8 to 10% is growing steadily rather than transforming the industry. Our custom software development scoping in fintech plans against that reality.
Why Market Size Figures Disagree
The same definitional problem documented on our outsourcing and app data pages, and more severe here than either.
The Spread
Published figures for the fintech market in 2026 range from roughly $180 billion to over $500 billion, with projections between $1 trillion and $1.76 trillion for various future years.
What Causes It
(cite index=”41-1″>Different sources frame size differently, usually because one tracks market value and another tracks annual revenue. Founders should know the difference before quoting numbers to investors.</cite>
One Named Estimate
(cite index=”42-1″>Fortune Business Insights values the global fintech market at $460.76 billion in 2026, projecting $1.76 trillion by 2034 at 18.2% CAGR.</cite>
How to Use Any of Them
Check whether the figure measures market value, annual revenue, or transaction volume, and which segments it includes. Three defensible answers differ by an order of magnitude.
Digital Lending and BNPL
Better-evidenced than market sizing, because government and central bank sources publish here with stated methodology.
BNPL Volume
(cite index=”45-1″>Buy now pay later reached $70 billion in US transaction volume in 2025 with 91.5 million US users, per Richmond Fed Economic Brief EB 26-05 published March 2026.</cite>
A Structural Change to That Segment
(cite index=”45-1″>FICO began incorporating BNPL data into credit scores in 2026, which fundamentally changes the risk profile of users who had previously treated BNPL as credit-invisible.</cite>
The SMB Lending Shift
(cite index=”46-1″>The share of small business financing applicants seeking funds from online fintech lenders increased from 17% in the 2020 survey to 29% in the 2025 survey, per the Federal Reserve Banks 2026 Report on Employer Firms.</cite>
Small Business Credit Demand
(cite index=”46-1″>60% of surveyed employer firms applied for financing during the prior 12 months, with operating expenses the most common reason at 56% and expansion at 46%.</cite>
Why This Data Is Stronger
Central bank surveys publish methodology and sample. Our data analytics work weights sources on exactly that basis.
Payments and Infrastructure
The segment where fintech has genuinely restructured behaviour, with the most reliable figures coming from national payment systems.
Real-Time Payment Scale
(cite index=”45-1″>India leads on real-time payment volume growth, with UPI processing more than 130 billion transactions in FY2024.</cite>
Payment Adoption Leadership
(cite index=”45-1″>China leads on payment adoption with over 90% of adults using digital payments, and on transaction volume.</cite>
Segment Composition
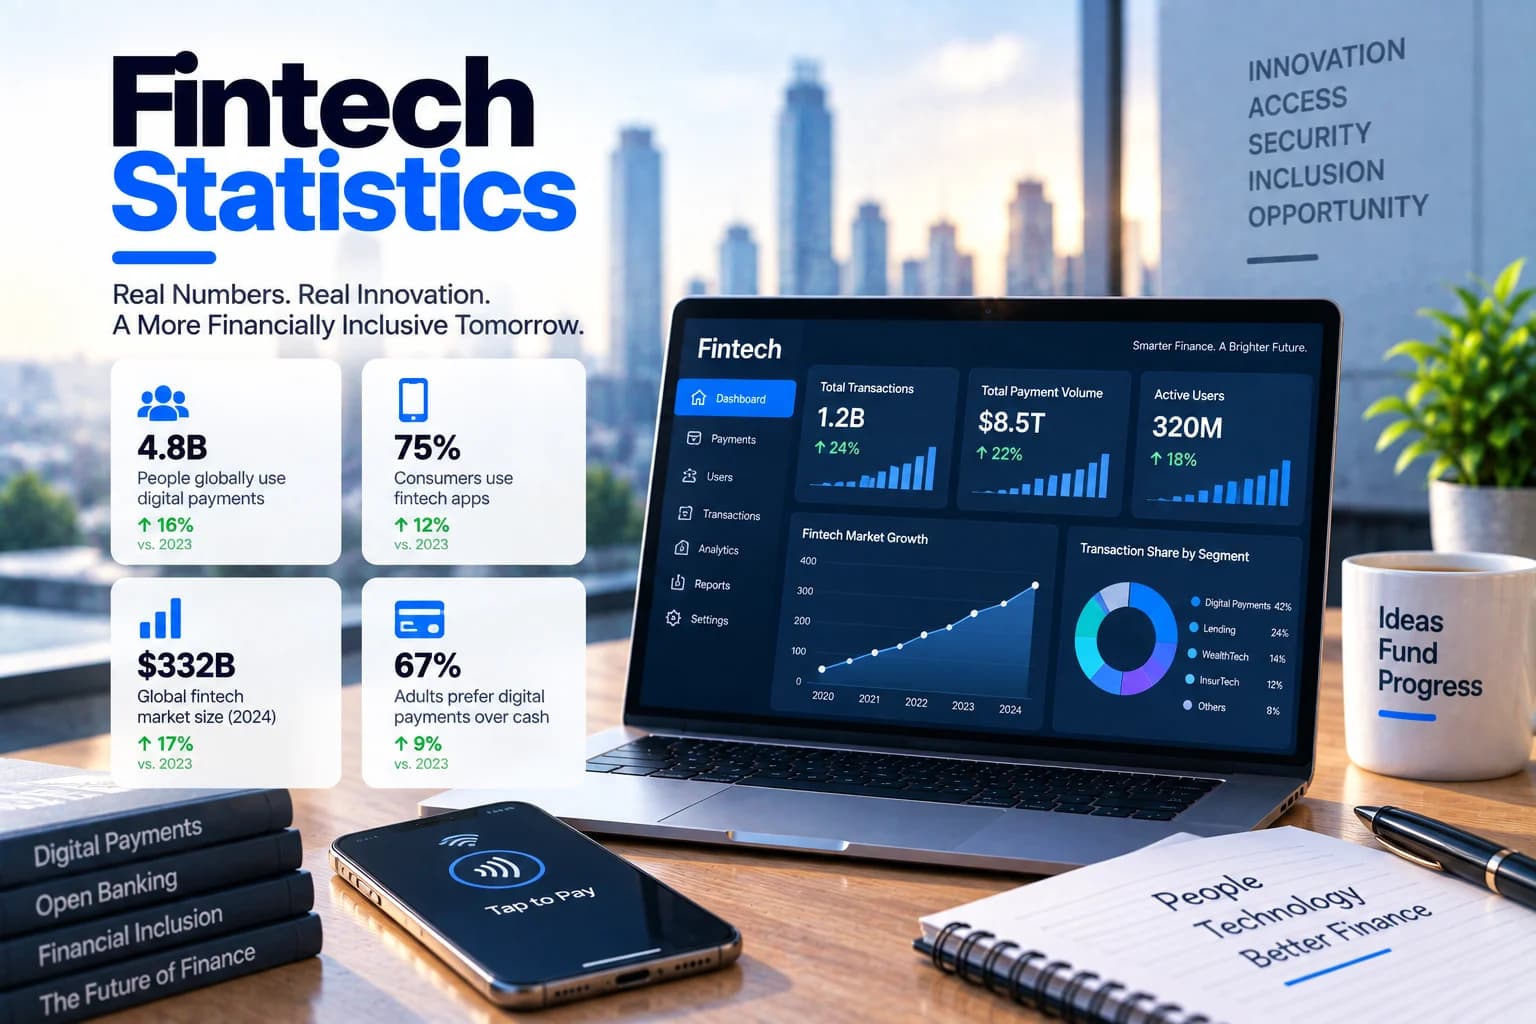
(cite index=”42-1″>Payments dominate the fintech market at 53%, with lending at 22%, insurance technology at 14%, wealth and investment platforms at 12%, and banking infrastructure with open banking at the remaining 11%.</cite>
Embedded Finance Sizing
(cite index=”40-1″>The embedded finance market is estimated at $85.8 billion in 2025, projected to reach $370.9 billion by 2035 at 15.8% CAGR, per Future Market Insights.</cite>
Infrastructure Implication
Payments carry the majority of the category. Our payment gateway integration work sits where the volume actually is.
Funding and Valuation Reset
The clearest evidence of the shift from growth-funded expansion to unit economics, documented in our fintech trends analysis.
The Multiple Correction
(cite index=”42-1″>The median valuation multiple for growth-stage fintech companies has settled at approximately 7x revenue, down from the 20x multiples common at the 2021 peak.</cite>
Funding Levels
(cite index=”44-1″>Global fintech investment for 2025 has been tracked in the $44 billion to $58 billion range across thousands of individual deals</cite>, with the spread again reflecting differing methodologies rather than disagreement about direction.
Where Momentum Sits
(cite index=”41-1″>Embedded finance, B2B payments, infrastructure rails, compliance tooling, and workflow-linked financial services have stronger momentum than consumer applications.</cite>
Regulatory Developments
(cite index=”45-1″>EU MiCA covering crypto became fully effective in January 2025, EU DORA covering digital resilience became effective January 2025, and EU PSD3 covering payments is in the legislative process.</cite>
What the Reset Means for Builders
A 7x multiple rewards durable revenue rather than user growth. Our API development work in fintech reflects that priority.
FAQs
How much of banking has fintech actually taken?
About 5%. Fintech companies captured approximately $150 billion of the roughly $3 trillion global banking revenue pool in 2024 per McKinsey, projected to reach 8 to 10% by 2030. Meaningful growth rather than displacement of incumbents.
Why do fintech market size figures vary so much?
Because some track market value, some annual revenue, and some transaction volume, across different segment definitions and projection years. Published 2026 figures range from roughly $180 billion to over $500 billion for what is described as the same market.
How large is buy now pay later?
BNPL reached $70 billion in US transaction volume in 2025 with 91.5 million US users, per a Richmond Fed economic brief published March 2026. FICO began incorporating BNPL data into credit scores in 2026, which changes the segment’s risk profile.
Are small businesses using fintech lenders more?
Yes, substantially. The share of financing applicants seeking funds from online fintech lenders rose from 17% in 2020 to 29% in 2025, per Federal Reserve Banks survey data. Overall, 60% of employer firms applied for financing in the prior 12 months.
What has happened to fintech valuations?
They reset sharply. Median growth-stage multiples settled around 7x revenue, down from 20x at the 2021 peak. Global fintech investment for 2025 has been tracked between $44 billion and $58 billion depending on methodology.
Which fintech segments are largest?
Payments dominate at roughly 53% of the market, followed by lending at 22%, insurance technology at 14%, wealth and investment platforms at 12%, and banking infrastructure with open banking at 11%.