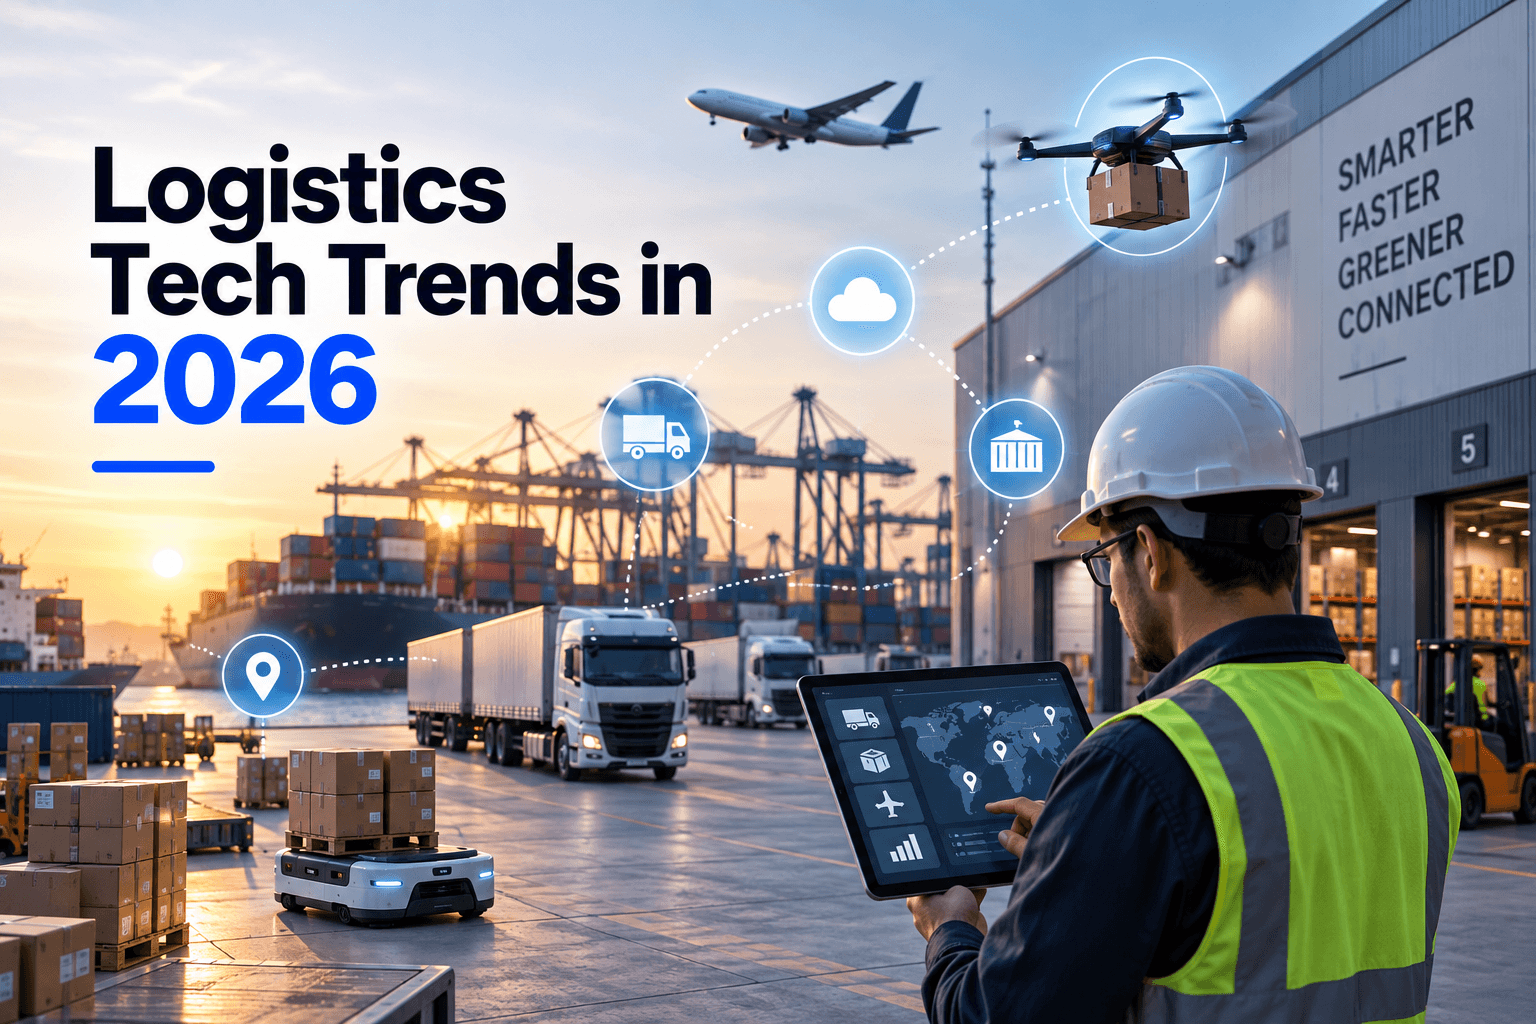
Logistics technology spending shifted after several years of supply disruption, from optimising for cost alone toward maintaining visibility and absorbing shocks. That reordering explains most current investment, including the sustained interest in visibility platforms and the more cautious approach to automation than the sector’s coverage suggests. This piece covers where spending is going, which constraints determine what works, and why data quality rather than analytics sophistication remains the limiting factor across most of the sector.
Visibility Became the Priority Purchase
Knowing where things are and when they will arrive turned out to be more valuable than marginal cost optimisation, because disruption is expensive and unpredictability compounds through a supply chain. This is now the most common first technology investment in logistics operations.
Shipment-Level Tracking Across Carriers
Consolidated visibility across multiple carriers and modes, rather than checking each provider’s portal separately.
Predicted Arrival Over Reported Status
Estimated arrival based on current conditions rather than scheduled dates. Useful because it enables intervention while there is still time.
Exception Management as the Actual Product
Nobody watches a dashboard continuously. Value comes from flagging what deviates and routing it to someone who can act.
Data Quality Is the Limiting Factor
Visibility platforms depend on carrier data feeds of highly variable quality. Our api-integration-services work spends more effort on normalisation than on integration.
Customer-Facing Visibility as Differentiation
Passing accurate expectations to customers reduces enquiry volume and is increasingly expected rather than a differentiator.
Resilience Over Pure Efficiency
Optimising a network to its absolute lowest cost removes the slack that absorbs disruption. Several years of disruption made that trade-off visible, and planning now weighs resilience alongside cost rather than treating it as waste.
Multi-Sourcing and Route Alternatives
Maintaining qualified alternatives rather than single lowest-cost paths, which costs more in steady state and less across a disrupted year.
Inventory Positioning Reconsidered
Strategic buffer stock at network points rather than minimum inventory everywhere. A reversal of a long-standing direction.
Scenario Modelling in Planning
Modelling disruption scenarios rather than only optimising expected conditions. Requires planning tools that support alternatives rather than one plan.
Supplier Risk Visibility
Understanding dependencies below the first tier, which most organisations discovered they lacked entirely during disruption.
Systems Implication
Planning systems must model alternatives and constraints rather than producing a single optimised answer. Our enterprise software development work covers this.
Warehouse Automation Economics Have Shifted
Automation interest is high and adoption is more measured than coverage implies, because the economics depend heavily on volume stability, labour cost, and facility characteristics. The trend is toward incremental and flexible automation rather than fully automated facilities.
Incremental Over Full Automation
Automating specific tasks rather than whole facilities. Lower capital, faster payback, and considerably less risk if volumes change.
Flexible Systems Over Fixed Infrastructure
Mobile robots and modular systems that can be redeployed, rather than fixed conveyor infrastructure committing a facility to one flow.
The Payback Calculation
Depends on labour cost, volume stability, and facility layout. Automation that works in one operation frequently does not in a superficially similar one.
Software Determines the Return
Automation hardware performs to the quality of the system directing it. Our software development work treats the control layer as where the value sits.
Labour Complement Rather Than Replacement
Most successful deployments reduce the physical burden of specific tasks rather than removing roles, which also eases adoption.
Data Standards and Integration Reality
Logistics involves many parties exchanging data, and the practical state of that exchange is worse than the sector’s technology narrative suggests. A substantial amount of coordination still happens by email, spreadsheet, and phone, and that is the real constraint on most improvement.
Legacy Exchange Formats Persist
Established electronic data interchange remains widespread. Modern API exchange is growing and coexisting rather than replacing.
Manual Coordination Is Still Common
Email and spreadsheets carry more logistics coordination than most technology discussion acknowledges. That is where the recoverable waste is.
Master Data Inconsistency
The same location, product, or partner identified differently across systems. This blocks more improvement than any analytics limitation.
Integration as the Actual Project
Most logistics technology projects are integration projects. Our erp-integration work reflects where the effort genuinely goes.
Why This Matters Before Analytics
Sophisticated analysis on inconsistent data produces confident wrong answers. Data foundations come first regardless of how unappealing that is.
What Has Been Overstated
Several logistics technology directions have received sustained attention with limited production deployment. Distinguishing them from what is shipping helps direct investment usefully.
Autonomous Long-Haul Trucking
Continued testing, limited commercial deployment, and timelines that have repeatedly extended. Not a planning assumption for this decade’s operations.
Drone Delivery at Scale
Operating in specific corridors and use cases rather than as general delivery. Regulatory and economic constraints remain unresolved.
Blockchain for Supply Chain Provenance
Extensively piloted with minimal production persistence. The underlying problem was data sharing between parties, which integration addresses more cheaply.
Fully Automated Dark Warehouses
Exist in specific high-volume contexts and remain uneconomic for the majority of operations. Incremental automation is the deployed reality.
The Planning Position
Our predictive analytics work in logistics prioritises data foundations and visibility over emerging technology bets, because that is where measurable return currently sits.
FAQs
What is the biggest logistics technology priority now?
End-to-end shipment visibility, specifically consolidated tracking across carriers with predicted arrival and exception flagging. Disruption made unpredictability expensive, which moved visibility ahead of marginal cost optimisation as the first investment.
Why is resilience being prioritised over efficiency?
Because optimising a network to its lowest cost removes the slack that absorbs disruption. Several years of disruption made that trade-off visible, so planning now weighs qualified alternatives and buffer positioning alongside cost.
Is warehouse automation worth it?
It depends on labour cost, volume stability, and facility layout, and automation that works in one operation frequently does not in a similar one. The current direction is incremental and flexible automation rather than fully automated facilities.
What limits logistics analytics?
Data quality and master data consistency. The same location, product, or partner identified differently across systems blocks more improvement than any analytical limitation, and sophisticated analysis on inconsistent data produces confident wrong answers.
Is autonomous trucking a realistic planning assumption?
Not for this decade’s operations. Testing continues, commercial deployment remains limited, and timelines have repeatedly extended. Treat it as a watch item rather than something to plan network design around.
Where should a logistics operation start with technology?
Master data consistency and carrier data integration, then visibility with exception flagging. Both are unglamorous and both are prerequisites for anything more sophisticated producing reliable results.